Insurance Claim Guide for Roof Damage
Navigating roof insurance claims can be tricky. Use our step-by-step guide to get the coverage you deserve without the headache.
What to Do Immediately After a Storm
The hours and days following a severe storm are critical for your insurance claim. In Northwest Florida, where high winds and hail are common, taking the right steps early can make or break your ability to get a full roof replacement covered.
Step 1: Document Everything
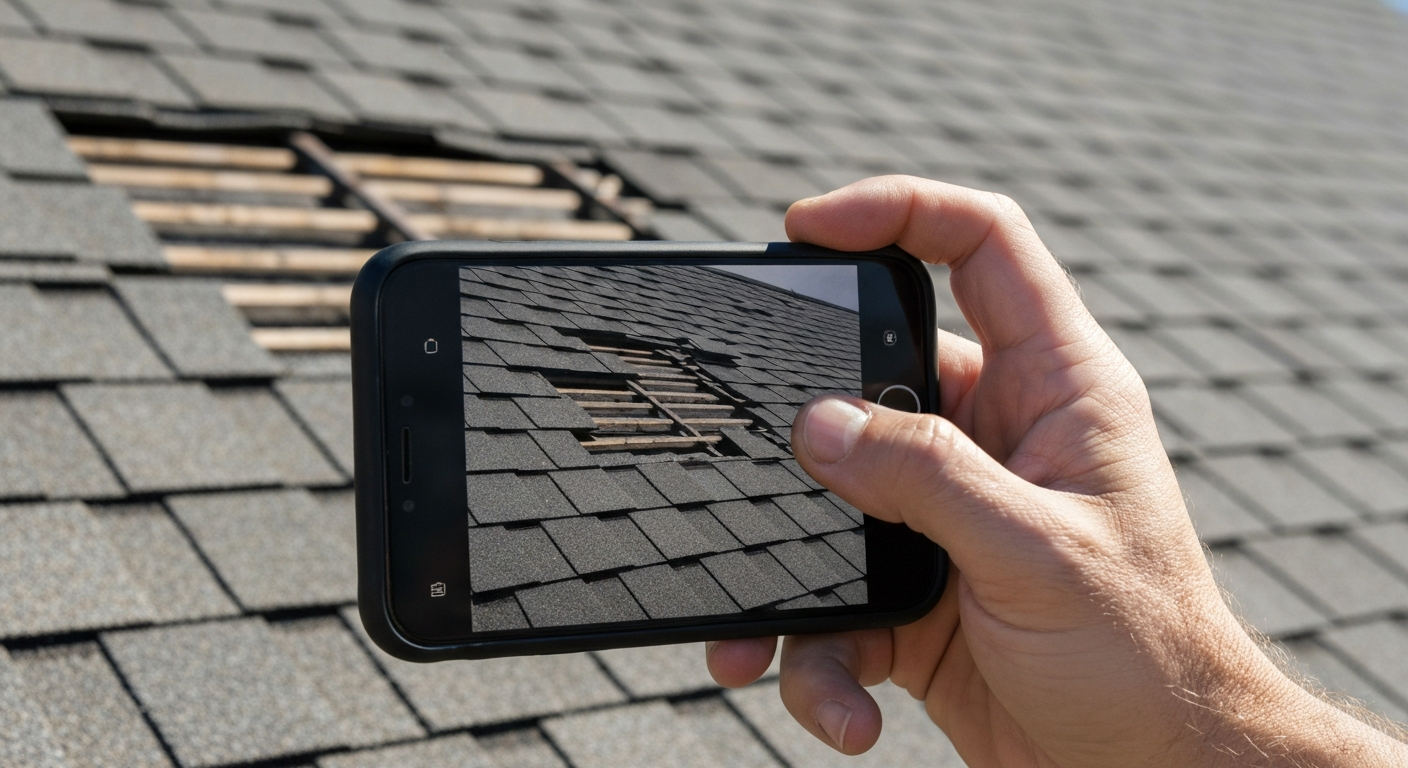
Before you touch anything or call your insurance company, take detailed photos and videos of the damage. Document both the exterior of your home and any interior leaks or water stains.
- Take photos of the entire house from all angles.
- Zoom in on specific shingle damage, missing metal panels, or fallen debris.
- Document damage to gutters, fences, and window screens.
- Keep a log of the date and time the storm occurred.
Understanding Your Policy: ACV vs. RCV
Actual Cash Value (ACV)
ACV pays you for the value of your roof minus depreciation. If your roof is 15 years old, the insurance company only pays for the remaining life value.
Replacement Cost Value (RCV)
RCV is the "gold standard." It pays for the full cost of a new roof at today's prices, regardless of age. You only pay your deductible.
The "Supplementing" Process: Why It Matters
Insurance adjusters often miss critical details like mandatory Florida Building Code requirements or specific local labor rates. "Supplementing" is the process where your contractor submits additional line items to the insurance company to ensure the job is done correctly.
Our Advocacy Process:
- • Code Compliance: We ensure the insurance company pays for mandatory items like drip edge and high-wind fastening schedules.
- • Hidden Damage: If we find rotted wood after the tear-off, we document and supplement it immediately.
- • Material Verification: We ensure the scope matches the quality of materials your home deserves.
Don't File a Claim Alone
Get a professional inspection first to confirm there is actual storm damage. We'll even meet your adjuster on-site to advocate for your home.
Need a Professional Opinion?
Stop guessing about the condition of your roof. Get a free, comprehensive inspection with full photo documentation.